Every December the same phone call comes in. A buyer has found the place, signed the contract and wants the keys before the kids finish school. Then someone mentions the lender's settlement team is running on a skeleton crew. Then the valuer can't get out until next week. Then the calendar runs out.
This year the calendar runs out faster than usual.
George Sourris, Legal Practice Director at Empire Legal, has put together a clear guide to the 2026 Queensland property shutdown. His headline point: the industry stops for ten days this Christmas, not eight. You can read George's full breakdown here. In this article I'll look at the same dates from the finance side, because that's usually where the time disappears.
The dates that matter
Here are the key dates from George's guide:
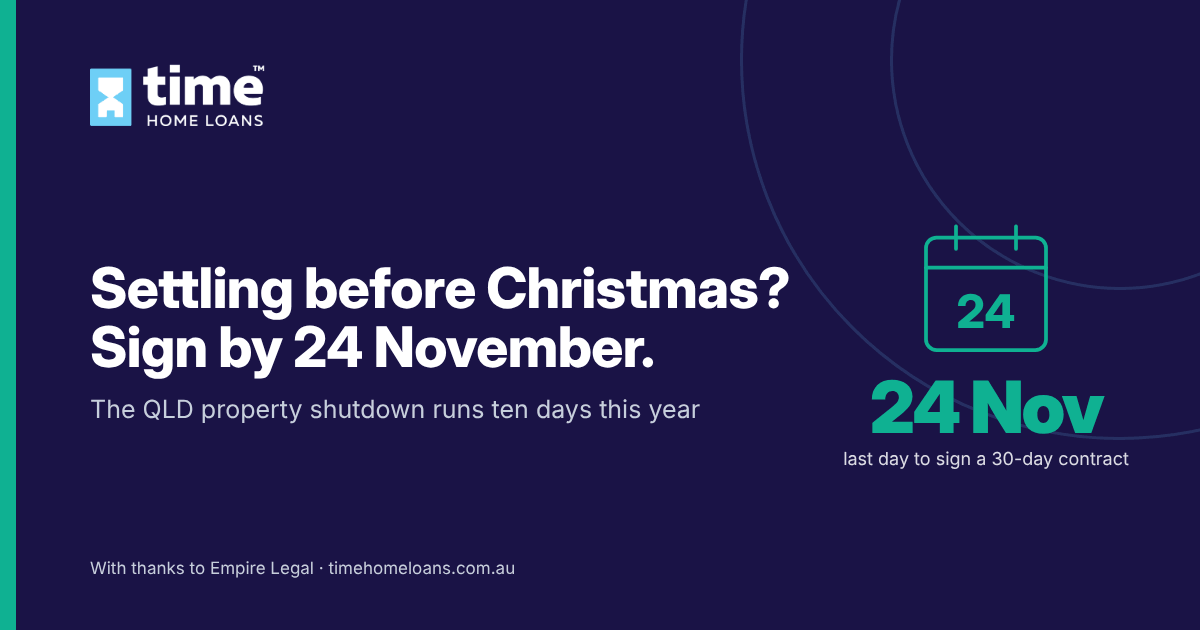
- Tuesday 24 November 2026: the last day to sign a standard 30-day contract and still settle in 2026
- Thursday 24 December 2026: the last business day to settle this year (and Christmas Eve is a part-day public holiday from 6pm)
- Friday 25 December 2026 to Sunday 3 January 2027: the shutdown window, which includes the REIQ contract shutdown period of 27 to 31 December
- Monday 4 January 2027: the first business day of the new year (anything that falls inside the window rolls to here)
Hot Tip: Work backwards from 24 December, not forwards from the day you sign. A contract signed on 25 November with a 30-day settlement already lands in January.
Why finance is usually the bottleneck
Lenders don't close for all of December. But a lot of their people take leave and the volume of settlements everyone is trying to squeeze in before Christmas goes up. So the queue gets longer while the team gets smaller.
That affects three things:
- Valuations. Valuers are busy too. A valuation that would take two or three days in March can take a week or more in December.
- Formal approval. Conditional approval is not the finish line. The lender still has to issue unconditional approval and loan documents. Then you still have to sign and return them.
- Settlement booking. Your lender has to be ready to settle on the day. George makes the point that a Christmas Eve settlement is risky because there's no next-day fix if something goes wrong.
George also flags something that catches people out every year. If a settlement is delayed, finance approvals and valuations can expire and need reissuing. That adds days you probably didn't plan for.
Is a 21-day finance period realistic in December?
Possibly. But be honest about it. George's guide suggests anything under 21 days for a pre-Christmas settlement is risky. I agree.
Here's how I'd think about it:
- If you have a current pre-approval and nothing has changed (same job, same income, no new debts), a shorter finance period is more achievable.
- If your pre-approval is more than a few months old, assume it needs refreshing. Lenders reassess.
- If you're self-employed, buying a unit or buying something unusual, build in extra time. These are the deals where a valuation or a policy question is most likely to slow things down.
At Time Home Loans we offer 7-day finance terms for buyers who are ready (approval still depends on the lender). In December, the preparation matters even more than the clause.
What about a January settlement?
A January settlement is not a disaster. For some people it's the sensible choice. But it can cost money if you're paying interest on a bridging loan or waiting on the sale of your current home. George mentions this in his guide and it's worth running the numbers before you commit to either date.
Example:
- Bridging loan balance: $400,000
- Interest rate: 7.5% p.a. (illustrative only)
- Interest for an extra 14 days: about $1,150
That may be worth paying to avoid a rushed settlement. Or it may not. The point is to decide on purpose.
A November checklist
If you want to settle in 2026, get these moving in November:
- Refresh your pre-approval (or get one if you haven't)
- Have your payslips, tax returns and statements ready to go on the day you sign
- Ask about ordering the valuation as early as the lender allows
- Get your contract reviewed by a solicitor or conveyancer before you sign
- Know your finance date and building and pest date (and put them in your phone)
Note: George also covers cooling-off periods, clause 6.2 extensions and off-the-plan contracts in his guide. Those are legal questions, so please read his article or speak to your own solicitor about them.
In a nutshell
The shutdown is ten days this year. The last day to sign a standard 30-day contract and settle in 2026 is 24 November. If finance is part of your purchase (and for most people it is), start now rather than in the second week of December.
If you're buying before Christmas and want to check your finance timeline, call us on (07) 3194 0888 or book a time online. We'll tell you straight whether your dates are realistic.
Thanks to George Sourris and the team at Empire Legal for permission to reference their work. Time Home Loans doesn't pay or receive referral fees for introductions to Empire Legal.
This article is general information only and does not take into account your objectives, financial situation or needs. It is not legal advice. Dates are as published by Empire Legal and current as at 29 October 2026. Lending criteria, fees and charges apply.